Key Businesses · Family-Owned Businesses
Family business attorneys, in writing.
Relatives own it, run it and work in it, and much of what they agreed may never have been written down. Legal should settle ownership, roles and what happens when an owner leaves before a retirement, an illness or a disagreement decides it.
01 Is this you
What usually brings family businesses here.
If two or more of these are live right now, you are the reason this page exists.
- GovernanceDecisions are made around the kitchen tableOperating agreements, bylaws and shareholder agreements set who decides, how votes count and how profits are shared.
- Buy-sellNo one has agreed what happens when an owner leavesA buy-sell agreement settles in advance how an owner’s interest is transferred, valued and funded on retirement, disability or death.
- Family on payrollOwners are also employeesWhen shareholders work in the business, compensation, termination rights and incentives have to match the ownership terms.
- HoldingsThe building sits inside the operating companyHolding companies and separate real estate entities keep ownership and property apart from the operating business.
- Next chapterKeep it in the family, or sell itA transfer to a family member or key employee often means seller financing or a management buyout; an outside sale has its own terms.
02 How we work with you
Counsel in the room, before the decision.
Family businesses changing ownership or planning succession have outgrown occasional advice but rarely justify a full-time general counsel. Fractional general counsel covers that ground on an ongoing basis.
That means an attorney who knows the family and the company, keeps the governing documents current as roles change, and works alongside your accountant and estate planning advisers, with more of that time during a transfer, a buyout or a sale and less in steadier years.
03 From clients
In the words of the firm’s clients.
“I've had a business relationship with Jeff for several years. He's helped me review contracts, make contracts and is amazing at translating lawyer-speak into English. He helped me navigate a particularly tricky situation with an employee that was leaving…”
“Starting my own hair salon was a dream come true, but I had no idea where to begin when it came to the legal side of things. That’s when I found Next Era Legal, and I’m so glad I did. Eric was absolutely amazing—professional, approachable, and incredibly knowledgeable.”
“Eric is an excellent attorney. He is responsive, detail-oriented, and explains things clearly and concisely. I consider him to be a go-to resource for all things business law. I highly recommend Eric and look forward to working with him in the future.”
Three of the reviews on the firm’s Google listing. Read every review, in full
 Case studyThe Reciprocal Buyout Offer
Case study
Two against two. A fair price anyway.
When four partners could not agree on a price, negotiating harder was not the answer. See the binding mechanism that made a fair price the rational choice.
 GuideStarting a Business
Free guide
How to launch now without legal gaps to fix later.
Five checks before anything goes to market: a business plan that attracts investors, the right entity, a name that is legally safe, the licenses that apply, and your trademarks, contracts and insurance.
Free checklist
How to close an LLC so it stays closed.
Walking away does not close the company. Follow the California and Texas steps in the order they must happen: approvals, debts and claims, final tax filings and the right form, so nothing is left open behind you.
Featured video
See succession planning in practice.
 10:02
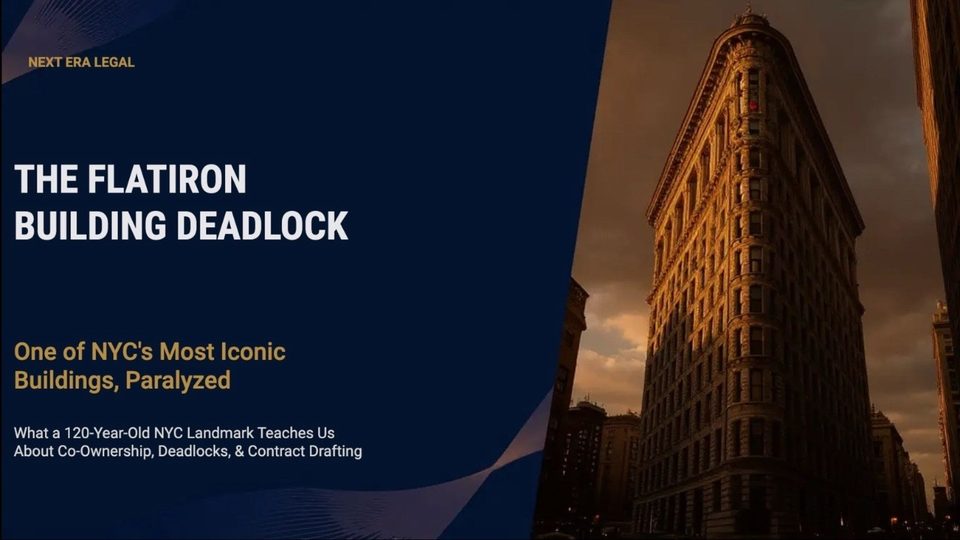
One of New York City's most iconic buildings sat completely vacant for years, and it had nothing to do with the economy or the real estate market.
Watch the video More short videosShort answers
A minute on succession planning.
Short videos from Next Era Legal on the questions clients ask most. Each one plays here, and the arrows step through the rest.
Watch 8 short videos on succession planning
 0:40CAN your business partner FIRE you?
 0:27Most Business Owners Ignore Their Operating Agreement Until It’s Too Late
 0:31How 50/50 Partnerships Create Deadlock And Disaster
 0:24How a Messy Divorce Destroyed a Multi-Million Dollar Business
 0:39What Goes Wrong in a Business Succession Plan?
 0:34How To Draft A Partnership Agreement That Prevents Costly Disputes
 0:27The Legal Mistake Most Businesses Make Before It's Too Late
 0:30The Smart Way To Structure A 50-50 Partnership
Further reading
More on succession planning.
 Case studyThe Reciprocal Buyout OfferRead the case study
 BlogHow to Sell an HVAC BusinessRead the article
 BlogHVAC Contract PlaybookRead the article
Also worth reading
04 Questions we hear
Questions about counsel for family businesses.
- 01
What is fractional general counsel for a family-owned business?
A senior lawyer on your legal work, without a full-time hire.
Fractional general counsel for a family-owned business is a lawyer who provides the strategic guidance an in-house general counsel would, without the commitment of a full-time hire. Next Era Legal's version suits companies whose legal needs have outgrown occasional advice, including family businesses that are changing ownership or planning succession.
More on Fractional General Counsel - 02
What should family owners put in writing?
Ownership, management, profit distribution and how shares can move.
Family owners should put clear expectations on ownership, management and profit distribution in the operating agreement, bylaws or shareholder agreement. Those documents usually limit when and how interests can be transferred, so an unwanted outsider cannot acquire one, set voting thresholds for major decisions, and say how directors and officers are chosen. Where owners already disagree, Next Era Legal represents companies and individual shareholders and looks to negotiation or mediation before litigation.
Read more - 03
What does a buy-sell agreement settle?
What happens to an owner's interest when they retire, are disabled, die or leave.
A buy-sell agreement for a family business defines how an owner's interest is transferred when that owner retires, becomes disabled, passes away or otherwise leaves. It also sets how the interest is valued, from a fixed-price formula to an appraisal, and how the purchase is funded. In the agreements Next Era Legal drafts, that funding is often life or disability insurance written into the agreement to provide the cash.
More on business succession planning - 04
How do you handle relatives who work in the business?
Their employment terms are coordinated with their ownership terms.
Relatives who work in a family business are handled by coordinating the shareholder or operating agreement with their employment contracts, covering compensation, termination rights and incentive structures. Next Era Legal pairs that with key person planning for the sudden loss of an owner or executive, and explains the plan to the employees, investors and family members it affects.
- 05
Should we pass the business to the next generation or sell it?
That is your decision; counsel structures either path.
Passing a family business to the next generation or selling it is the owners’ decision, and either path needs legal work planned in advance. A transfer can be a sale, a gift or a reallocation of shares or membership interests, and a transfer to a family member or key employee often involves seller financing or a management buyout. An outside sale is its own negotiated transaction. Next Era Legal coordinates with your financial, tax and estate planning advisers so the plan and documents line up.
- 06
When should a family business call a lawyer?
Before a generational transfer, a new owner or a sale, not during a crisis.
A family business should call a lawyer when it wants to plan a generational transfer, when its owners have no buy-sell agreement, when a new owner joins or a family member steps back, when governing documents no longer reflect who owns and runs the company, and when outside investment or a sale offer is coming. Waiting for a crisis or an imminent retirement, in Next Era Legal's experience, leaves fewer options.
Eight locations, one teamTypically replies the same business day
 Los AngelesBeverly Hills Office(310) 734-4791Mon–Fri
 Orange CountyNewport Beach Office(949) 209-4184Mon–Fri
 San DiegoUniversity City Office(619) 323-3445Mon–Fri
 San FranciscoSoMa Office(650) 374-1337Mon–Fri
 HoustonUptown Office(713) 255-2098Mon–Fri
 Metro DetroitTown Center Office(313) 887-4788Mon–Fri
 Washington, DCK Street OfficePhone coming soonMon–Fri
 MiamiBrickell Office(305) 686-4866Mon–Fri